By using our website, you agree to the use of cookies as described in our Cookie Policy
Is Long-Term Vehicle Financing Right for Your Organization?
Fleet expansion doesn't happen in a vacuum. You need trucks, vans, or sedans on the ground—and you need them funded without crushing your operating budget. Long-term vehicle financing sounds like the answer: spread the cost over six, seven, even eight years, and watch those monthly payments drop. But stretch a loan too far and you're paying interest long after the warranty expires. You're also stuck with aging assets while competitors rotate their fleets every three years.
We've seen organizations fall into both traps. They either lock themselves into terms they can't escape or avoid financing altogether and miss growth windows. The truth sits somewhere in between. Long-term vehicle financing works—when it matches how you actually use your fleet and what you plan to do with those vehicles down the line. The question isn't whether it's good or bad. It's whether it fits your operation, your cash position, and your exit strategy.
Monthly Relief Versus Total Damage
Extending a vehicle loan drops your payment. That much is obvious. A $40,000 truck financed over four years might cost $900 a month. Push it to seven years and you're closer to $600. For organizations running thin margins or scaling fast, that extra breathing room matters. It frees up capital for payroll, inventory, or emergency reserves.
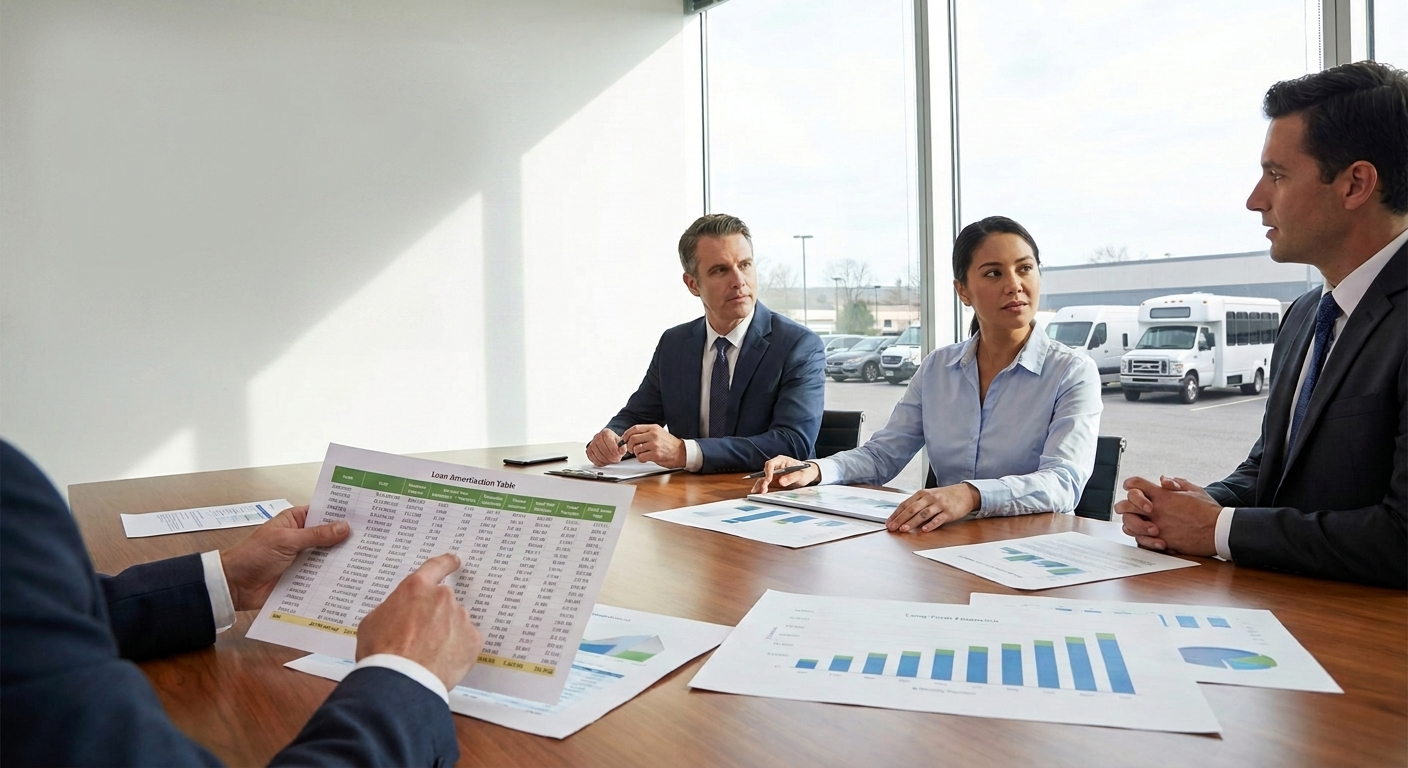
But lower payments don't mean lower cost. You're paying interest for three extra years, and most lenders don't offer the same rates on longer terms. By the time you're done, that truck might've cost you $48,000 instead of $43,000. That's real money—and it compounds across a fleet of ten or twenty vehicles. Before you sign, run the full amortization schedule. See what you're actually paying, not just what leaves your account each month.
Depreciation Moves Faster Than Your Loan Balance
Vehicles lose value the second they leave the lot. Most drop 20% in the first year, then another 15% the year after. Finance one over seven years and you'll spend the first four underwater—owing more than the vehicle's worth. That's negative equity, and it limits your options. Can't trade it in without writing a check. Can't sell it without covering the gap. Can't pivot your fleet strategy without taking a loss.
Organizations with high-mileage needs hit this wall even harder. A delivery van running 50,000 miles a year isn't worth much at year five, but you're still two years from paying it off. Meanwhile, repair costs climb and downtime eats into revenue. If your vehicles work hard, they age faster. Plan for that before you stretch the term.
When Lower Payments Actually Make Sense
Long-term financing isn't inherently bad. It just has to match your reality. Here's where it tends to work:
- Your fleet needs are stable and predictable—you're not pivoting industries or changing vehicle types in the next few years
- You're prioritizing cash flow preservation over total cost, especially during growth phases or seasonal dips
- The vehicles you're financing hold value longer—executive sedans or executive shuttle vehicles, not high-mileage work trucks
- You plan to keep the vehicles past the loan term, so you'll eventually own them outright and operate payment-free
- Your organization has solid credit and can negotiate competitive rates even on longer terms
Where Long Terms Start to Crack
Not every fleet fits the long-term model. Push it too far and you're creating problems, not solving them. Watch for these red flags:
- Your vehicles rack up heavy mileage or take a beating—construction trucks, delivery vans, anything running six days a week
- You need flexibility to upgrade technology or shift fleet composition as your business evolves
- You're already carrying significant debt and adding more interest-heavy obligations strains your balance sheet
- You don't have a clear plan for what happens at the end of the term—trade-in, resale, or keep running the vehicle
- The interest rate you're offered on a longer term is noticeably higher than a shorter one, erasing the monthly savings
What the Numbers Should Tell You
Before committing to any term length, run the real math. Don't just look at the monthly payment—calculate total interest, estimate resale value at payoff, and factor in maintenance costs as the vehicles age. If you're financing five trucks over seven years, that's 35 vehicle-years of interest, depreciation, and upkeep. Compare that to a four-year term and see what the difference actually costs.
Most organizations underestimate how much they'll spend on repairs once vehicles hit year five or six. Transmissions, brakes, electrical issues—they all add up. If you're still making loan payments while also covering $3,000 repair bills, the monthly savings stop feeling like savings. Build a full cost-of-ownership model before you sign anything. If the numbers still work, move forward. If they don't, consider shorter terms or alternative structures like leasing.
Other Ways to Fund a Fleet
Long-term financing isn't the only option on the table. Depending on your situation, these alternatives might fit better:
- Shorter-term loans with higher payments but lower total interest and faster equity building
- Leasing arrangements that keep you in newer vehicles with predictable costs and built-in upgrades
- Fleet management programs that bundle financing, maintenance, and insurance into one monthly fee
- Lines of credit for flexible vehicle acquisition without locked-in repayment schedules
- Vehicle subscription services for organizations that need short-term access or frequent fleet rotation
Documentation Keeps You Honest
Whatever financing structure you choose, keep every document. Loan agreements, payment schedules, mileage logs, maintenance records—all of it. If you're deducting interest or depreciation, the IRS will want proof. If you're trading vehicles in or selling them, buyers and lenders will want history. Mixing personal and business use? Track it down to the mile. Sloppy records cost you deductions, resale value, and credibility with lenders on your next round of financing.
Getting Help Before You Commit
If your fleet financing involves multiple vehicles, variable usage patterns, or a mix of loan terms, bring in a pro. A financial advisor or fleet consultant can help you model total cost, compare structures, and avoid commitments that don't match your operational reality. They'll also spot tax advantages or financing incentives you might miss on your own. It's not just about getting approved—it's about setting up financing that supports your organization's growth without boxing you in.
Matching Terms to Your Timeline
Long-term vehicle financing works when it aligns with how you actually use your fleet and where your organization is headed. If you need cash flow relief and plan to keep vehicles for the long haul, it's a solid play. If your fleet turns over fast or your needs shift year to year, you're better off with shorter terms or more flexible arrangements. Organizations operating crew vans, medical transport vehicles, or adult daycare transportation should carefully evaluate financing terms that match their specific usage patterns. The answer isn't universal—it's specific to your operation, your budget, and your ability to manage assets over time. We help organizations fund fleets the right way, with terms that match their reality and advisors who understand the difference between a good deal and a good fit.
Let’s Build a Smarter Fleet Together
We know that every organization’s needs are unique, and the right financing can make all the difference in your fleet’s performance and your bottom line. Let’s talk about your goals and find a solution that keeps your vehicles working for you—not the other way around. Call us at 877-824-8267 or request information to start a conversation about your next move.
‹ Back
Recent Posts
-
Is Long-Term Vehicle Financing Right for Your Organization?
November 6, 2026
-
Can Executive Livery Vans Be Customized for Business Travel?
October 23, 2026
-
Should You Choose a Custom Wheelchair Van or a Factory Model?
October 9, 2026
-
When Is It Time to Replace Your Medical Transport Vehicle?
September 25, 2026
-

Can One Mobility Van Handle Every Transportation Need?
September 11, 2026
Site by